Billionz Multi-Asset Weekly Newsletter

Equities Under Pressure as Nifty Extends Losing Streak Amid Broad-Based Sell-Off
Global Developments:Brent continuing to hover above USD 100 mark and US treasury yields soaring to multiple decade highs is weighing on risk sentiment
US September jobs report came in weaker than expected. Market is pricing in a 20% chance of a rate hike in October 28th policy
RBI rate decision is due on Wednesday, 7th October and a 25bps hike seems likely.
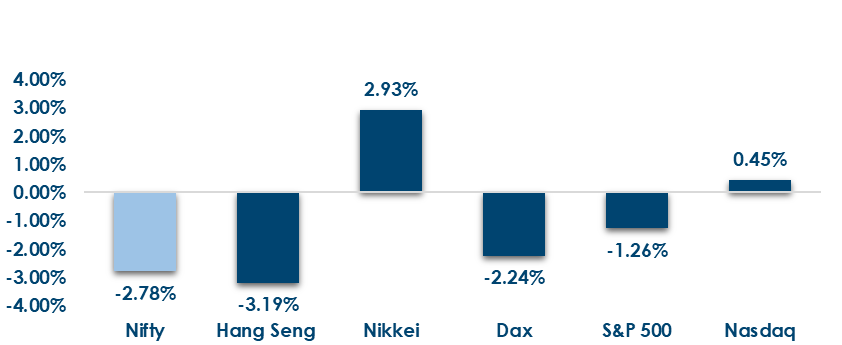
Global Equity Markets:
Domestic Equities:
- Nifty50 trades at 18.8x trailing and 16x forward earnings, indicating a relatively lower valuation compared with the broader market.
- Midcap100 and Smallcap250 trade at elevated valuations of 27.5x/23.8x and 27.6x/24x on trailing/forward earnings, respectively..
- India VIX increased to 14.46 from 12.16 last week.
- 212 stocks in NSE500 are currently above their 200 day moving average
- FPIs sold net USD 3.8bn of domestic equities in September and USD 1bn in October so far.
- Sun TV Network (+16.90%), Cupid (+15.70%) and Sterlite Technologies (+14.10%) were the top gainers, posting strong double-digit gains during the week.
- On the downside, PB Fintech (-16.00%), Patanjali Foods (-12.10%) and IFCI (-11.90%) were among the worst performers, reflecting broad-based weakness across several stocks.
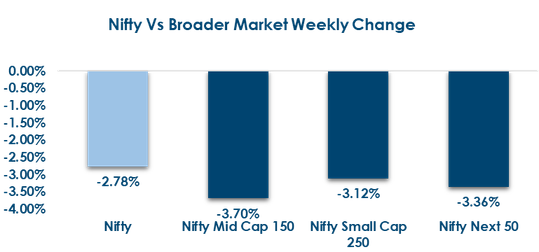
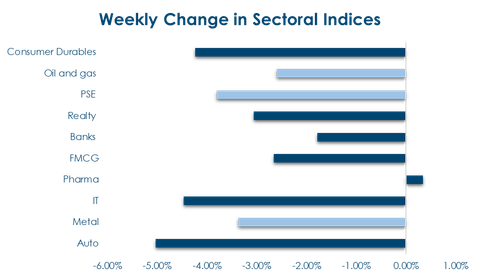
Below are the graphical representations for how key benchmark indices performed this week & how sectoral indices performed this week:
Fixed Income
Global Rates:
- Global 10Y yields were mixed, with the US and France rising 3.7bps and 10.2bps respectively, while Germany and South Korea declined sharply by 18.2bps and 18.5bps.
India Rates & Flows:
- The domestic 10Y yield rose to 7.21% from 7.12%, while 1Y and 5Y OIS increased to 6.27% and 6.72%; FPIs sold USD 2.3bn of domestic bonds in September.
Real Estate
- Redbrick Offices is in advanced talks to raise around $60mn from new and existing investors, with the funds aimed at expanding its managed workspace presence across India.
- Chowman Hospitality has appointed an investment banker to raise ₹150–200cr through a minority stake sale, targeting institutional investors to support its pan-India expansion
IPOs :
- IPO activity is set to surge next week, with 20 issues targeting a combined ₹1,292 crore, including four mainboard and 16 SME offerings.
- The busy IPO calendar comes amid elevated bond yields, Rupee weakness and strong FPI outflows, providing a key test of domestic retail and HNI demand.
Private Equity & Venture Capital
- Early-stage funding remained active across AI, cybersecurity and healthcare, with Unveilr AI raising ₹16.7cr, Zaperon ₹7cr and Aignosis ₹4cr in fresh capital.
- Strategic technology also attracted capital, with Yohan and Michelle Poonawalla investing in Optimized Solutions, highlighting continued interest in defence, aerospace, space and nuclear technologies.
Commodities
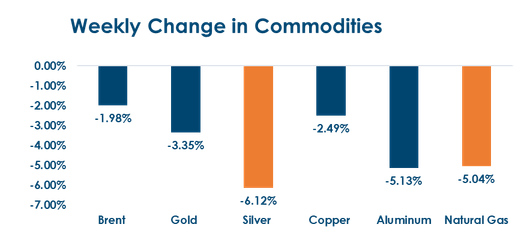
Commodities declined broadly this week, with Silver (-6.12%), Aluminum (-5.13%), Natural Gas (-5.04%) and Gold (-3.35%) leading the losses, while European Natural Gas (+3.73%) was the notable gainer
What’s New in the World of Wealth Management
The week delivered a genuine stress test for India’s fixed income and currency markets. The 10-year G-Sec yield touched 7.19%, a two and a half year high, on September 28 as Brent crude crossed $106 per barrel on Strait of Hormuz supply disruption fears, before easing marginally to 7.15% by month-end. The rupee briefly crossed Rs 96 to the dollar on September 29, with likely RBI intervention providing intraday support though the central bank did not confirm it. Sagarmala Finance withdrew its Rs 600 crore bond issue and SIDBI cancelled a Rs 6,000 crore debt sale mid-week as high-coupon bids made pricing unviable, a sign that the bond market is repricing borrowing costs faster than issuers anticipated. The most consequential corporate fundraise of the week cut through this difficult backdrop: Bajaj Finance’s board approved a Rs 17,500 crore capital raise comprising a Rs 11,700 crore QIP and Rs 5,800 crore through promoter warrants, the company’s first major fundraise since November 2023 and a strong signal of confidence from India’s most closely tracked NBFC in an environment where cost of funds is visibly rising.FPI selling accelerated sharply into month-end, with September 29 alone seeing Rs 9,980 crore in single-day outflows, the largest since March 2026, taking cumulative CY2026 FPI equity outflows to Rs 4,26,783 crore.
Our Views: What we Like?
Equities: Nifty50 has fallen for 8 straight weeks and ended below the 200 day SMA on Thursday. April low of 22182 is crucial. We saw an intraday rebound from similar levels on Thursday We may see a short covering bounce towards 23200 and could trade a 22200-23200 range over next few weeks If 22200 breaks, we could potentially look at another 5-7% drop to 20900.We may see the beta factor play out now and sell off, on break below 22200, if it does happen may not just be limited to large cap space.
Fixed Income: Yield on the domestic 10y surpassed recent high of 7.14% . 1y OIS is pricing in 4 hikes. 5y OIS looks a good receive around 6.80%.Those looking to raise Dollar funding especially up to 1 year should consider raising INR and swapping given the dislocation in forward curve.
Commodities:Energy prices are likely to be headline driven. We continue to remain bullish on precious metals at current levels. Given the deteriorating global macro, we have tempered our bullishness on base metals.
FX: Higher US bond yields are pushing the Dollar higher against G10. Exporters are advised to hedge cautiously only to extent of in-hand orders while Importers are advised to hedge on any dips.