Billionz Multi-Asset Weekly Newsletter

Domestic Equities Slide Amid Broad-Based Sell-Off, Smallcaps Bear the Brunt
Global Developments:
Mixed Earnings and lower Capex guidance resulted in a sell off in AI stocks this week
Drone strikes on Saudi Arabia and fears of a US/Israel strike on Iran after the midterms caused energy prices to spike
Risk off resulted in a rally in US Treasuries this week on safe haven demand.
Fed is widely expected to hold in its policy next week. A 25bps rate hike is likely in December though.
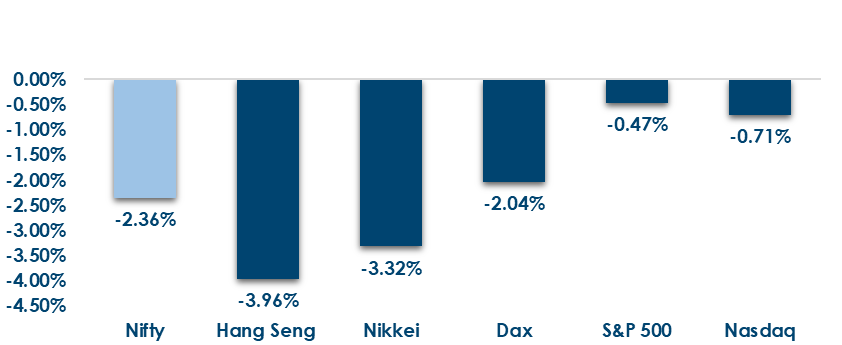
Global Equity Markets:
Domestic Equities:
- Nifty 50 trades at 19x trailing and 16x forward earnings, while Midcap 100 valuations stand at 27x and 24x, respectively.
- Smallcap 250 remains relatively expensive at 28.5x trailing and 24x forward earnings, despite the sharp correction in domestic equities.
- India VIX stands at 16.86 compared to last week close of 14.1.
- 120 stocks in NSE500 are currently above their 200 day moving average
- FPIs have sold net USD 5.4bn of domestic equities in October so far.
- International Gemological Institute Ltd. led the gainers with a 16.70% rise, followed by Tata Teleservices (Maharashtra) Ltd. at 12.30% and Ipca Laboratories Ltd. at 6.60%
- Himadri Speciality Chemical Ltd. fell 25.50%, followed by Swiggy Ltd. at 24.90% and Jindal Saw Ltd. at 23.00%.
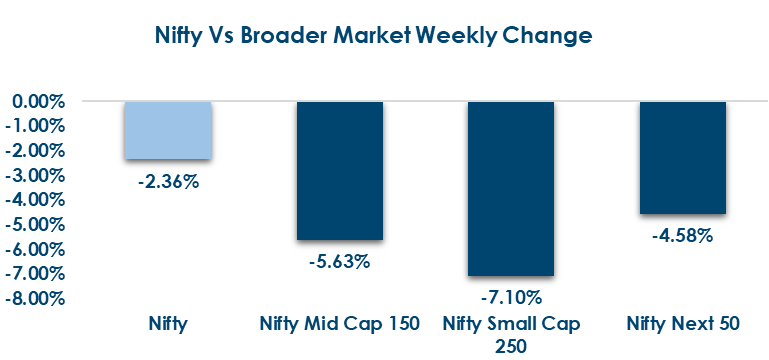
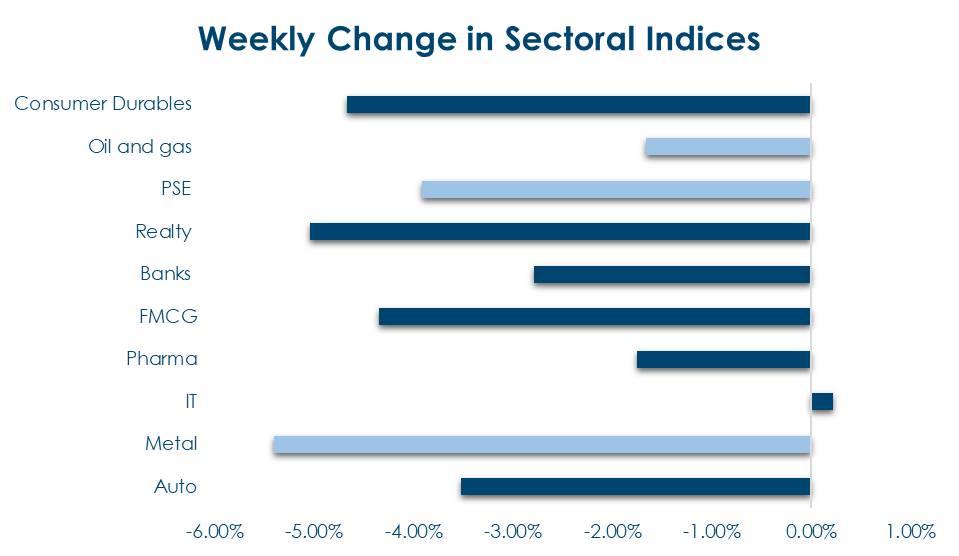
Below are the graphical representations for how key benchmark indices performed this week & how sectoral indices performed this week:
Fixed Income
Global Rates:
- 10-year bond yields declined across most major economies, led by the US (-14.5 bps), Japan (-11.1 bps) and Germany (-10.9 bps), while France was the outlier, with yields rising 8.1 bps.
India Rates & Flows:
- The domestic 10-year benchmark yield rose to 7.47% from 7.38% amid tight liquidity conditions, while 1-year and 5-year OIS rates edged higher to 6.58% and 6.82%, respectively. FPIs recorded net bond purchases of USD 100 million in October so far
Real Estate
- Bajaj Alternate Investment Management raised ₹950 crore in the first close of its maiden real estate fund, targeting ₹2,000 crore to invest in Grade A commercial offices, particularly in GCC-driven markets.
- Despite slower startup funding, investor interest remains strong in technology, healthcare, financial services and alternative investments.
IPOs
- New rules effective April 1, 2027, ease operational requirements, introduce a 10% liquid asset floor and permit performance-linked fees under PRIM, with a 25% cap on group AMC investments.
- The ₹30,213 crore fresh issue attracted strong institutional demand, with proceeds largely earmarked for Jio Infocomm debt repayment; listing is scheduled for October 28.
Private Equity & Venture Capital
- Funding fell to $234.8 million across 15 deals, led by Vegafin Capital ($106 million) and Even Healthcare ($50 million), with continued interest in financial services, healthcare and AI.
- Deal count rose to five from four, led by Mygate’s $84.2 million acquisition of AdOnMo, followed by Sagility’s $32.4 million acquisition of Chirok Health.
Commodities
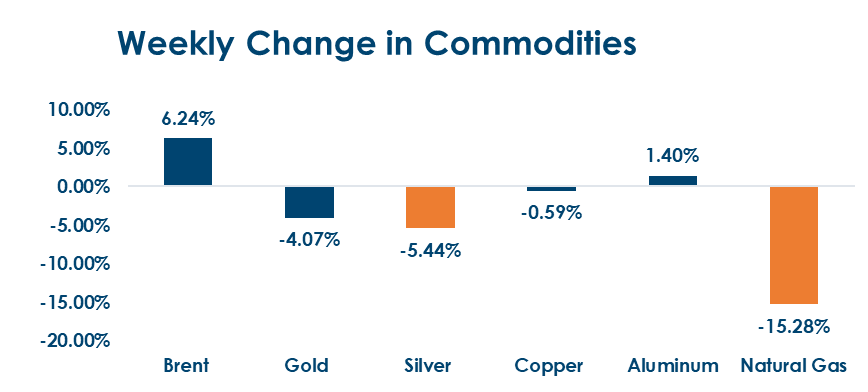
Brent crude surged 6.24% to $116.72/bbl, while WTI rose 1.83%; European natural gas gained 7.20%, but US natural gas plunged 15.28%. Precious metals weakened, with gold falling 4.07% and silver declining 5.44%, while aluminium rose 1.40% and copper slipped 0.59%.
What’s New in the World of Wealth Management
The SEBI Portfolio Managers Regulations, 2026, notified on October 12 and effective April 1, 2027, carry three operational changes that matter in practice for HNI and family office clients. Smaller PMS managers no longer need a dedicated dealing room below a prescribed AUM threshold, lowering barriers for boutique strategies. Net worth requirements now include a mandatory 10% liquid asset floor, and performance fees are permitted alongside a capped 1% management fee under the new PRIM route, aligning manager economics with client outcomes. Investments in group or affiliate AMC schemes under PRIM are capped at 25%, providing a structural safeguard against in-house product pushing that has historically been a concern in Indian wealth management. Jio Platforms’ ₹30,213 crore IPO closed with 22.19× overall subscription, led by 70.55× demand from institutional investors, attracting approximately ₹7.4 lakh crore in bids. With allotment scheduled for 26 October and listing on 28 October, attention shifts to the debut, while the fresh capital is expected to support debt repayment and strengthen financial flexibility.
Our Views: What we Like?
Equities: The move towards 23200 quickly fizzled out on Nifty50 validating our view that it was a short covering bounce. We continue to expect domestic equities to remain under pressure. 22200 is a crucial level on down side, break of which could trigger potentially another 5% down move. We prefer companies with high free cash flows and less leverage in current environment, making them less vulnerable to rising interest rates. We therefore prefer a tactical shift towards defensives.
Bonds and Rates: Higher oil prices, tight banking system liquidity are weighing on domestic bonds. 7.50% is a critical level for the 10y yield. We expect a 7.15-7.50% range for the 10y over next several weeks. Around 6.80% seems a good level to receive 5y OIS.
Commodities: We continue to remain bullish on precious metals and see the current dip as a good buying opportunity. We are neutral to mildly bullish on base metals and expect energy prices to remain headline driven.However, technically Brent consolidating above USD 100 per barrel is not a good sign. Break of USD 120 could trigger stops and result in a panic move.
FX: Ranges continue to hold as far as broad Dollar is concerned.USDINR again got supported around 94.20-94.40. It seems the pair has bottomed. However with RBI having imposed draconian curbs onshore, market participants aren’t able to freely express their view.