Billionz Multi-Asset Weekly Newsletter

Domestic Equities Outperform Global Peers, Led by Pharma and Broader Market Gains Amid Global Anti-AI Sentiment
Global Developments:
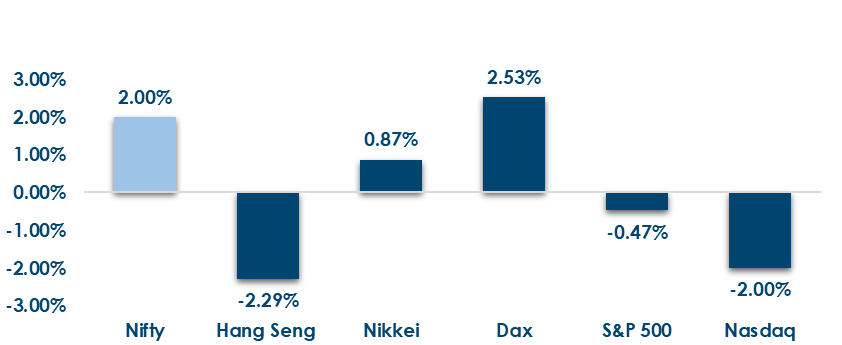
Fed held rates at 3.75-4.00% in a 10-2 vote, Fed Chair Warsh called financial conditions tighter but stopped short of “tight,”. Markets now price 85% odds of a December hike.ECB held its deposit rate steady, with Lagarde staying non-committal on the direction of the next move and reaffirming a meeting-by-meeting, data-dependent approach.BoJ held its policy rate at 1.25% this week following September’s hike, with reported pushback from PM Takaichi against further tightening weighing on the yen.US Midterms and Iran.Democrats hold an ~8.6-point generic ballot lead (50.8-42.2) heading into Nov 3, with late-week polls ranging D+4 to D+12. Reports point to the White House weighing renewed major strikes on Iran once midterms conclude, with US-Israel contingency planning and Yemen-linked fighting keeping tensions elevated through the week. Nasdaq posted its worst month in over a year on AI-capex-payoff anxiety.
Global Equity Markets:
Domestic Equities
- Nifty 50 trades at 19.2x trailing and 17x forward earnings, while Midcap 100 valuations stand at 27.5x and 24.9x, respectively.
- Smallcap 250 remains relatively expensive at 28.8x trailing and 24.5x forward earnings, compared to large-cap valuations.
- India VIX eased to 15.3 compared to previous week close of 16.86
- FPIs sold net USD 3.6bn of domestic equities in October
- 147 stocks in NSE500 are currently above their 200 day moving average
- Acutaas Chemicals (+27.60%), Ather Energy (+27.30%) and Piramal Pharma (+25.00%) were the top-performing stocks this week.
- CarTrade Tech (-22.40%), eClerx Services (-17.70%) and Dalmia Bharat (-16.70%) were the major laggards.
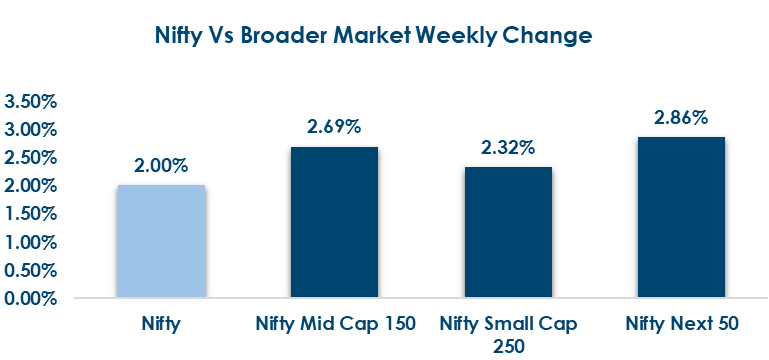
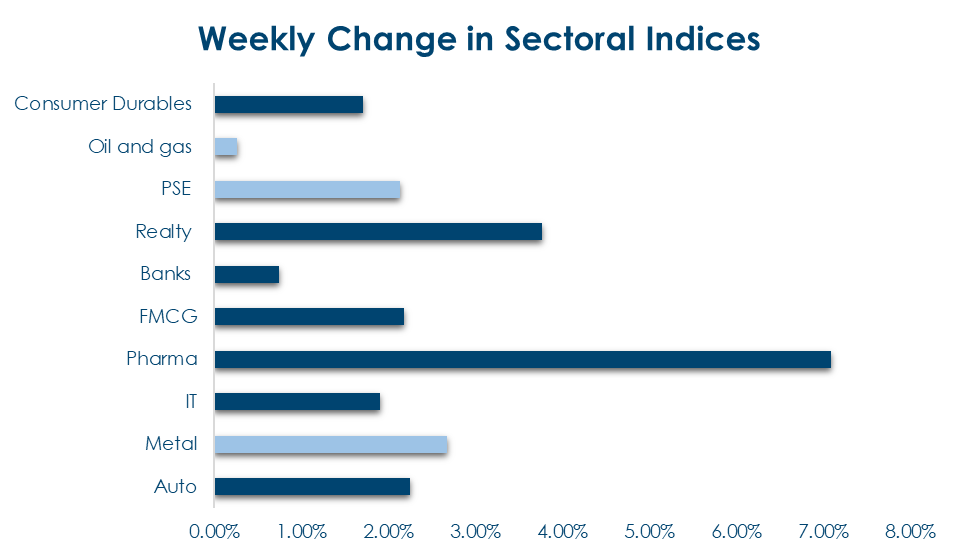
Below are the graphical representations for how key benchmark indices performed this week & how sectoral indices performed this week:
Fixed Income:
Global Rates:
- 10-year bond yields declined across most major economies, led by South Korea (-6.5 bps), the UK (-6.0 bps) and the US (-5.9 bps), while France was the outlier, rising 6.9 bps.
India Rates & Flows:
- The domestic 10-year benchmark yield fell 6 bps to 7.41%, while banking liquidity remained in a modest surplus of ₹30,000–50,000 crore. FPIs bought a net USD 1.1 billion of domestic bonds in October.
Real Estate:
- Bajaj Finserv’s alternative investment arm achieved the first close of its maiden real estate fund at approximately ₹950 crore, against a target corpus of ₹2,000 crore, including a greenshoe option.
- The fund will focus on Grade A commercial office developments through equity joint ventures with established developers, targeting returns through development-led value creation.
IPOs
- The mainboard IPO of Bombay Coated and Special Steels, worth ₹183.06 crore, is open for subscription until November 2, with listing scheduled for November 5.
- The SME segment sees four IPOs closing on November 3, while Vedant Poly Fabs opens on November 2, spanning electrical equipment, engineering and industrial sectors.
Private Equity & Venture Capital
- PE-VC activity increased to 28 companies this week from 16 last week, while disclosed funding declined to $120.4 million across 26 transactions from $234.8 million, indicating a shift towards smaller-ticket investments.
- Consumer technology, AI, enterprise technology, gaming and healthcare attracted investor interest, with Cent ($15 million), Simplismart ($14 million) and Live2.ai ($14 million) among the largest funding rounds.
Commodities
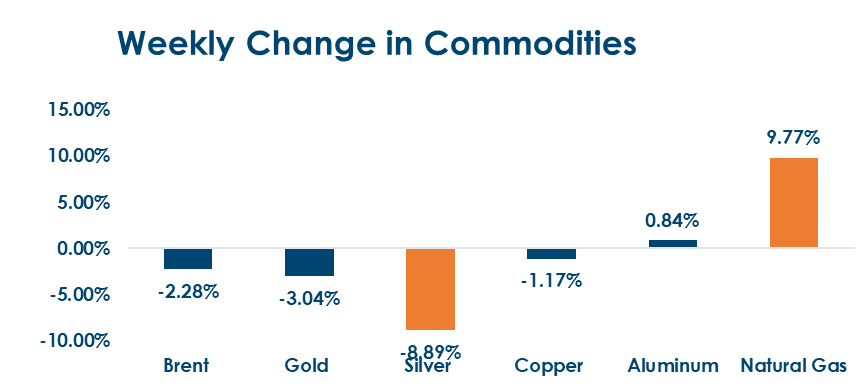
US and European natural gas prices surged 9.77% and 10.75%, respectively, while WTI crude rose 0.82% and Brent fell 2.82%. Gold and silver declined sharply by 3.04% and 8.89%, respectively, while copper slipped 1.17% and aluminium gained 0.84%.
What’s New in the World of Wealth Management
The SEBI regulatory agenda is expanding beyond PMS reforms, with a proposed overhaul of the SME IPO framework and a review of mainboard IPO and FPO regulations. The SME proposals include tighter profitability requirements, market-capitalisation-based listing eligibility and a greater role for institutional investors in assessing issuers. Separately, SEBI is examining the existing Issue of Capital and Disclosure Requirements framework. These developments are relevant for investors evaluating newly listed companies, as changes to listing eligibility and disclosure requirements could influence the quality of issuers entering public markets. The proposals remain subject to regulatory finalisation and should not be treated as effective rules.The Jio Platforms IPO was the capital-markets event of the week. India’s largest-ever IPO raised Rs 30,213 crore at Rs 1,119 per share and attracted 22.19 times overall subscription, with the QIB category subscribed 70.55 times. Shares listed at Rs 1,358 on October 28, a 21.36% premium to the issue price, and closed the first trading session at Rs 1,419, up 26.81%. On October 30, Jio Platforms reported a 13.7% year-on-year increase in quarterly net profit to Rs 8,389 crore, while operating revenue rose 11.4% to Rs 40,475 crore.
Our Views: What we Like?
Equities: Benchmark Nifty50 continues to remain in 22200-23200 range. Early reported earnings trends point to a divergent performance landscape, where infrastructure, renewable energy, and financial services are leading, while traditional pharmaceuticals and selective export segments face margin pressures.We lean towards stock picking based on strong thematic undercurrent and backed by strong free cash flows and low debt levels. We are in favor of gradually increasing the beta of the portfolio as valuations in broader markets have become more reasonable.
Fixed Income: We see 7.50% on benchmark 10y and 6.85% on 5y OIS as attractive to invest/receive. Credit also looks attractive with 10y AAA PSUs yielding about 8.30%.
Commodities: We remain neutral on base metals, bullish on precious metals and expect energy prices to remain headline driven.
FX: Energy is likely to be the dominant theme with currencies of energy surplus countries outperforming and those of energy dependent countries remaining under pressure. We see a 94.20-96.80 range for Rupee over next several weeks.