Billionz Multi-Asset Weekly Newsletter

FPI Inflows Reach USD 8 Billion in November as Mid and Small Caps Catch Up with Large Caps
Global Developments: Sticky US inflation prints highlighted by a hot October CPI and annual PPI running at +8.8% YoY (its fastest pace since November 2022) pushed Fed rate hike expectations sharply higher. A 25bps hike in December is now compared priced in.
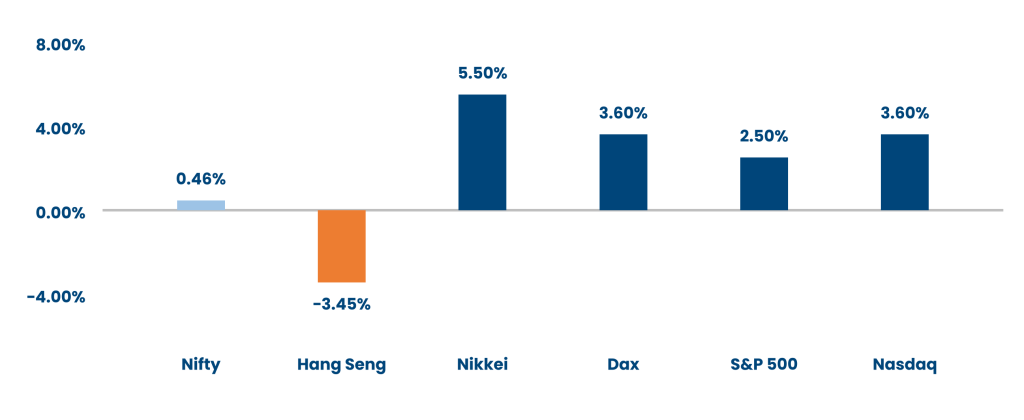
Wall Street digested an abrupt leadership shock on Thursday after Nvidia co-founder Jensen Huang stepped down as CEO, naming CFO Colette Kress as interim CEO. While semiconductor names saw heavy two-way volatility ahead of next week’s earnings, broader US and European benchmarks still logged solid weekly gains.
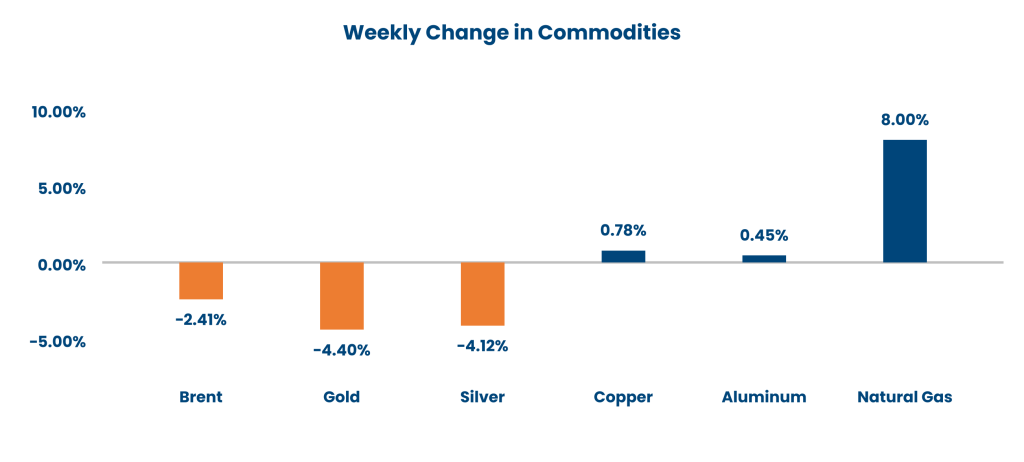
Crude whipsawed after President Trump stated the US no longer needed a deal with Iran alongside Houthi attacks on Saudi energy facilities. Brent however still finished the week -2.41% lower at $95.95 (vs $98.32 last week).
Global Equity Markets:
Domestic Equities:
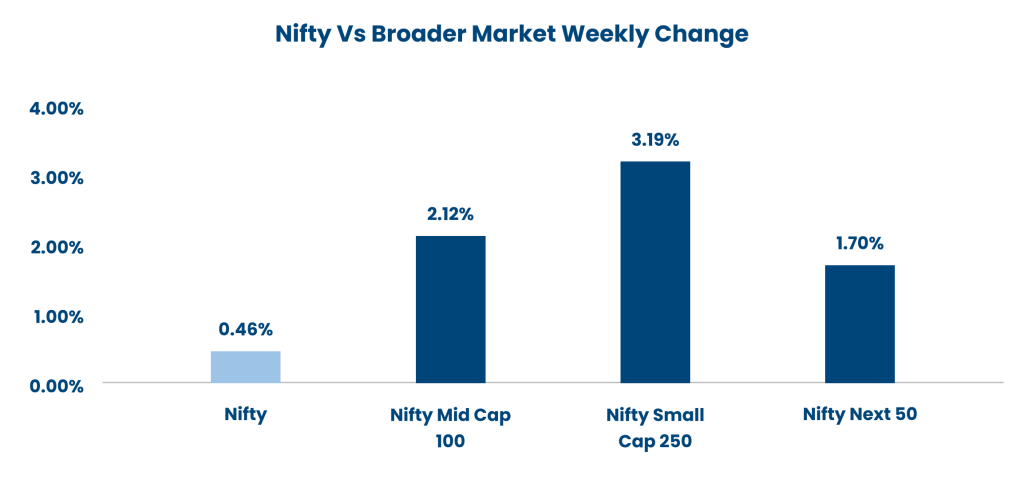
- Nifty 50 rose 0.46% to 25,144; Smallcap 250 (+3.19%) and Midcap (+2.12%) outperformed.
- Nifty 50 trades at 21.8x trailing and 18.5x forward earnings, while Midcap 100 valuations stand at 27.1x and 23.1x, respectively.
- Smallcap 250 trades at 29.8x trailing and 25.3x forward earnings.
- India VIX dropped sharply to 15.50 compared to last week close of 17.47.
- FPIs bought net ~USD 3.9bn of domestic equities this week, taking November MTD net inflows to ~USD 8.0bn.
- Kalyan Jewellers India led the gainers with an 18.0% rise, followed by Godrej Industries at 16.9% and Finolex Cables at 16.4%.
- Page Industries fell 12.8%, followed by NHPC at 7.6% and Concord Biotech at 6.1%.
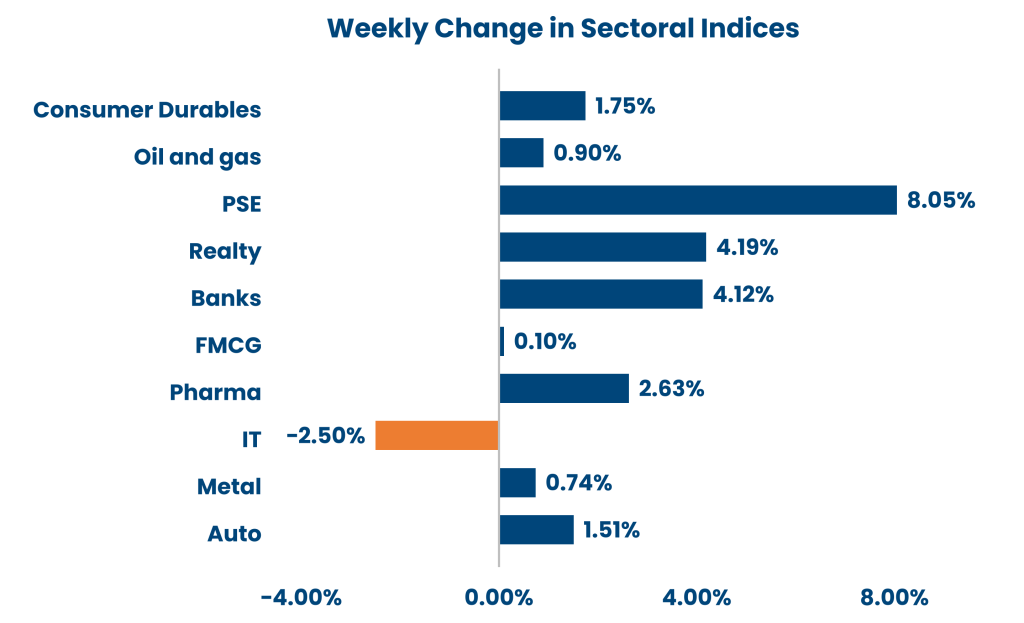
Below are the graphical representations for how key benchmark indices performed this week & how sectoral
indices performed this week:
Fixed Income
Global Rates: 10-year yields rose sharply across major economies, led by the US (+25.3 bps to 5.135%), Japan (+21.4 bps), the UK (+20.6 bps) and France (+18.9 bps).
India Rates & Flows: The domestic 10-year yield rose to 7.30-7.31% from 7.19% as US yields spiked and CPI crossed the RBI’s
6% band. 1y and 5y OIS rose to 6.51% and 6.61%; FPIs bought USD 71mn of bonds (November: USD 471mn).
Alternatives & Real Estate: DLF and Everstone are forming a joint venture to take a stake of at least 20% inIreo Pvt Ltd and other group companies, with DLF committing ₹3,750 crore (~$398 million). DLF’s aggregate economic interest is expected to be about 40%. The deal is subject to due diligence and approvals, with closing expected during 2027.
IPOs
- Fresh issuance remained limited this week, with market activity driven by listings and investor interest in recently listed companies.
- IPO activity is expected to pick up next week, with Crystal Crop Protection and Watrana Rentals scheduled to open for subscription.
Private Equity & Venture Capital
- PE-VC deals fell to 14 in the four-day week ended 13 November from 24, with value at ~$277 million versus $413 million. The largest was Bodhi Tree Systems’ ~$180 million majority stake deal for A2B.
- M&A slowed to six deals from seven, led by Delhi International Cargo Terminals’ ~$35 million acquisition of KSH Distriparks.
Commodities
Brent crude fell 2.41% to $95.95/bbl and WTI dropped
2.38%, while US natural gas surged 8.00% and
European natural gas declined 3.10%. Gold fell 4.40%
and silver 4.12%, while copper rose 0.78% and
aluminium 0.45%.
What’s New in the World of Wealth Management : Fresh issuance remained limited during the week, with market activity largely driven by listings and investor interest in recently listed companies. Looking ahead, IPO activity is expected to pick up next week, with Crystal Crop Protection and Watrana Rentals scheduled to open for subscription. AMFI data for October showed mutual funds recording net inflows of ₹1.74 lakh crore against net outflows of ₹1.33 lakh crore in September, while equity fund inflows fell about 14% to ₹32,994 crore and SIP contributions eased to ₹32,160 crore from September’s record ₹32,490 crore. SEBI also revised the accredited investor framework on 5 November, allowing AIF managers, SIF asset management companies and portfolio managers to verify an investor’s accreditation, with the status valid for three years.
Our Views: What we Like?
Equities :
Strong November FPI inflows (~USD 8.0bn MTD) continue to absorb domestic profit-taking, with mid- and
small-caps catching up (+2.12% and +3.19% WoW) after last week’s large-cap surge. 24800 remains strong
structural downside support on Nifty50, followed by 24300. We continue to remain overweight large caps and
domestic cyclicals (Metals, Realty, Auto).
Fixed Income :
Domestic bonds sold off tracking the sell-off in US treasuries. This upmove brings yields right back to the top of
our 6.90-7.30% target range, offering a fresh entry window to build long duration positions.
Commodities :
Precious metals faced near-term headwinds from the 25bp surge in US 10y yields, pulling Gold down 4.40%
below $3,900, though we maintain our structural portfolio allocation view. We stay constructive on base metals.
FX :
Our constructive view on the Dollar played out strongly this week as sticky US inflation and hawkish Fed
repricing pushed DXY higher. We continue to remain bullish on the Dollar in the near term. On USD/INR, we
continue to expect a 93.10-94.50 consolidation band anchored by RBI two-way intervention.