Billionz Multi-Asset Weekly Newsletter

Navigating Higher Yields, Oil Volatility and Shifting Global Markets
Global Developments:UST 10y surged toward 5.18%, the highest since the financial crisis, driven by hawkish Fed comments (Governor Barr), a hot PMI print, and rising odds of another October hike. Fed funds futures now price roughly 64% for October. Oil whipsawed on Iran headlines through the week. WTI/Brent fell for five straight sessions on reports of US-Iran side talks on a phased Strait of Hormuz reopening, before Houthi strikes on Saudi Arabia briefly pushed Brent to $108. WTI ended the week down about 7% while Brent was roughly flat to slightly higher, widening the Brent-WTI spread to its highest since May amid talk of a possible US diesel export ban.
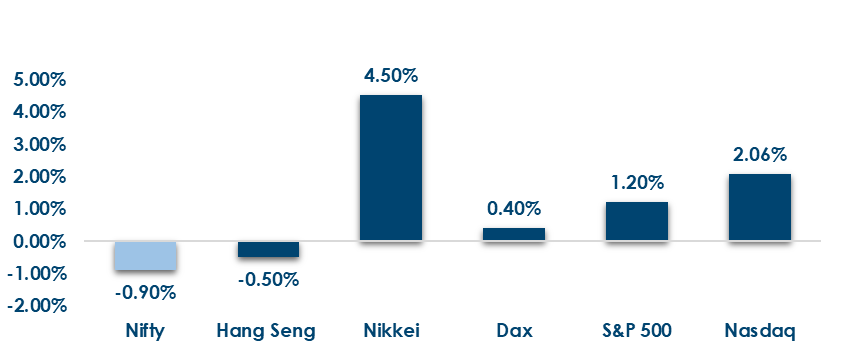
Equities shrugged off the bond selloff. Nasdaq hit fresh record highs and S&P 500/Dow posted weekly gains, as falling oil offset the yield surge.
Global Equity Markets:
Domestic Equities :
- Nifty50 trades at 19.4x trailing and 16.3x forward earnings, reflecting relatively moderate valuations versus the broader market.
- Midcap100 and Smallcap250 trade at elevated valuations of 28.5x/26x and 28.4x/25x, respectively, on trailing/forward earnings.
- India VIX increased to 12.16 from 11.39 last week.
- 253 stocks in NSE500 are currently above their 200 day moving average
- FPIs have sold net USD 1.8bn of domestic equities in September so far
- Whirlpool of India led the gainers with a 28.0% rise, followed by Engineers India (18.5%) and Carborundum Universal (13.7%).
- PB Fintech declined 34.9%, while Tata Chemicals and New India Assurance fell 17.7% and 10.3%, respectively.
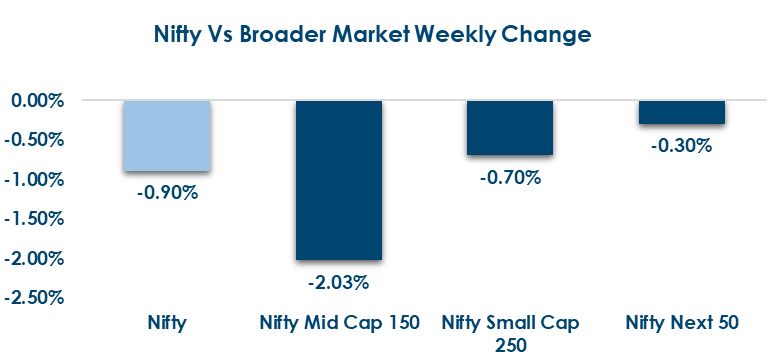
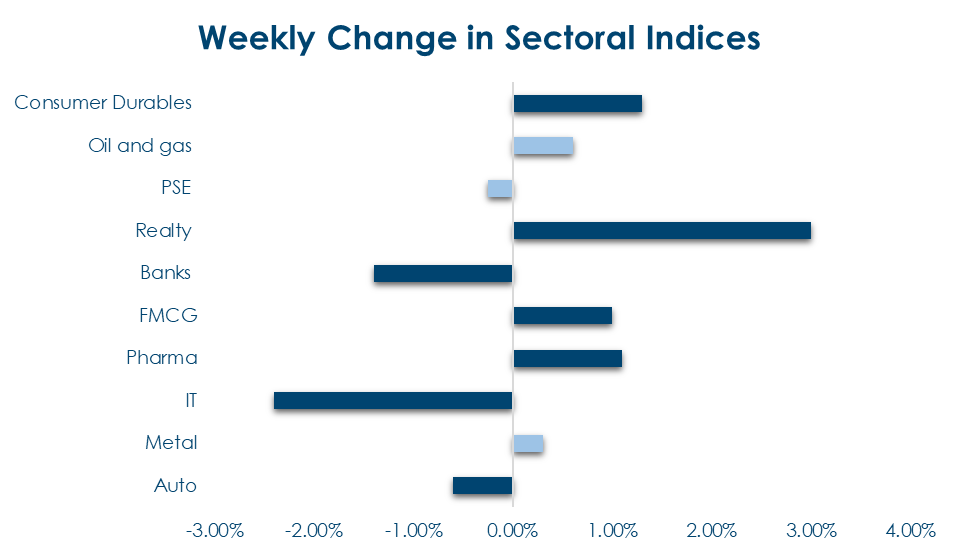
Below are the graphical representations for how key benchmark indices performed this week & how sectoral indices performed this week:
Fixed Income
Global Rates:
- Global 10Y yields rose sharply this week, led by France (+21.9bps), the US (+20.9bps) and the UK (+15.4bps), while China (-1.0bps) and South Korea (-8.7bps) bucked the trend.
India Rates & Flows:
- The domestic 10Y yield rose 5bps to 7.12%, with 1Y OIS up 9bps to 6.16%; despite surplus liquidity of over ₹4 lakh crore, FPIs have pulled out USD 1.5bn from domestic bonds in September so far.
Real Estate:
Srijan Realty is in discussions to sell DLF TechPark II for around ₹350–400 crore, with ICICI Prudential Alternate Investments and Alpha Alternatives emerging as leading bidders.
The transaction would allow Srijan to recycle capital from the operational office asset into development of adjoining land parcels, while highlighting rising domestic fund interest in commercial assets with established rental cash flows.
IPOs:
- IPO activity remains strong, with confirmed mainboard issues closing this week offering over ₹5,000 crore, led by JSW One Platforms’ ₹1,300 crore fresh issue plus ₹1,754 crore OFS.
- Early October will see several listings, including AceVector (formerly Snapdeal), while SME issuance remains active with multiple issues opening through the week.
Private Equity & Venture Capital:
- PE/VC activity softened sharply, with 22 companies raising $437 million in the week ended September 25, down from $1.53 billion across 23 companies the previous week, largely due to the absence of large-ticket deals.
- Energy transition, EVs and technology remained key themes, with Brahma AI and AMPIN Energy Transition each raising up to $100 million, alongside sizeable investments in Ultraviolette Automotive and Ema.
Commodities
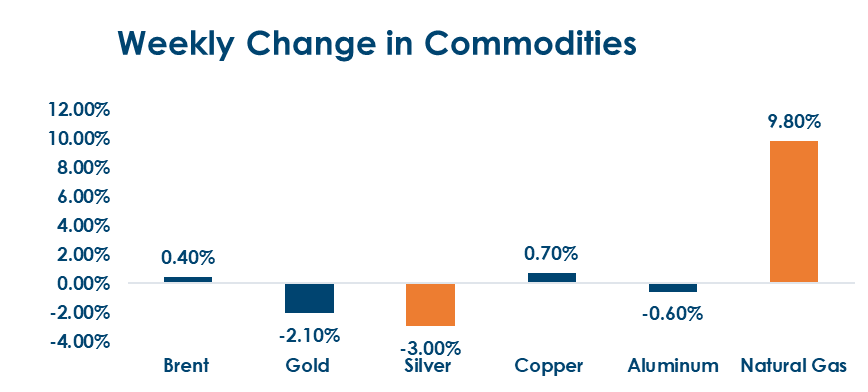
Commodity markets delivered mixed signals this week, with a sharp 7.9% decline in WTI contrasting with Brent above USD 100, a 9.8% surge in US natural gas and modest gains in copper.
What’s New in the World of Wealth Management
SEBI’s board meeting on September 24 approved the most significant overhaul of the PMS framework since 2020. The new SEBI Portfolio Managers Regulations, 2026 expand what a PMS can invest in, now including IPOs, foreign securities, and select unlisted debt instruments. For the first time, a PMS client can have up to 10% of their portfolio in investment-grade unlisted debt, opening a credit opportunity previously available only through AIFs. SEBI also introduced PRIM, a new route allowing PMS managers to build client portfolios using direct plans of mutual funds, ETFs, and SIFs at a management fee capped at 1% of AUM, with a Rs 25 lakh entry ticket. The entire PMS rulebook has been cut from 70 pages to 33 pages, a genuine effort to reduce compliance overhead and make the industry more accessible. Emkay Wealth projected India’s wealth management market to grow 2.5 times to $436 billion by 2034, putting all this regulatory reform in the context of how early India still is in the wealth product adoption curve.SEBI also eased the Accredited Investor framework this week. Investors with Rs 5 crore in securities market exposure can now be accredited directly by their AIF manager, AMC, or PMS provider without going through a third-party agency, and that accreditation is portable across products within the same group for three years.
Our Views: What we Like?
Equities: Nifty50 has fallen for 7 straight weeks. It however held on to the 23000 mark. Break below could result in a further 4-5% correction and a retest of April lows of 22182. Broader markets may also feel the heat this time as there are broad macro headwinds on account of higher US yields and elevated crude prices .We may be at an inflection point where it turns from being a market of active sector allocation and stock selection to broad macro headline driven price action.
Fixed Income: Domestic 10y benchmark bond yield is at the upper end of its 6.90-7.15% trading range. We expect the range to hold till Brent is below USD 110 per barrel. 5y OIS is good to receive close to 6.75-6.80% levels.
Commodities: While energy prices are likely to be headline driven, we believe Gold and Silver allocation is a must in any long term portfolio and current levels look attractive to start building positions.
FX: Rupee is likely to remain under pressure as US 10y yield curve settles above the 5% mark. Elevated Brent prices are likely to keep sentiment on the edge. Break of 96.10 could trigger a 0.5% move higher on USDINR.