Billionz Multi-Asset Weekly Newsletter

Domestic Equities Rally on Short Covering as IT Surges and STT Reconsideration Hopes Lift Sentiment
Global Developments: Rupee was the best performing Asian currency this week on RBI measures announced last week. Interbank and client activity was quite muted though given restrictions.
Despite the hotter than expected CPI print, US treasury yields came off. There are two factors at play here; dovish comments from Fed members (which keeps the probability of Fed hiking in Oct policy at mere 17%) and risk aversion driving safe haven demand for treasuries.
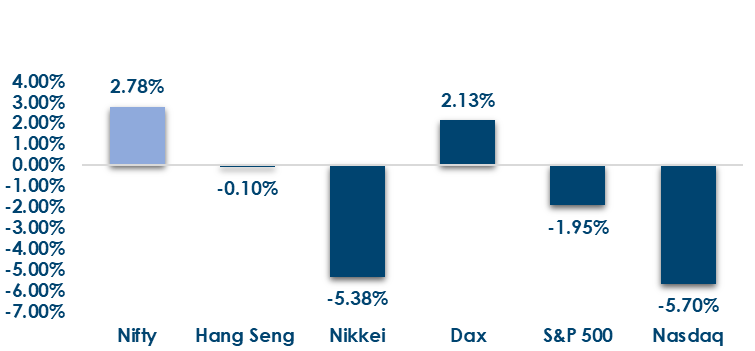
Global Equity Markets:
Domestic Equities :
- Nifty 50 is trading at 19.4x trailing and 16.4x forward earnings, while the Midcap 100 commands higher valuations at 28.2x and 26x, respectively.
- The Smallcap 250 remains the most expensive segment at 30.6x trailing and 26.4x forward earnings, indicating a significant valuation premium over large-cap stocks.
- India VIX stands at 14.06 compared to last week close of 14.3
- 270 stocks in NSE500 are currently above their 200 day moving average
- FPIs have sold net USD 5.4bn of domestic equities in October so far
- Tata Elxsi led the gainers with a 23.0% rise, followed by Gallant Ispat (+21.0%) and Tech Mahindra (+18.2%), reflecting strong buying momentum in these stocks.
- On the downside, Sterlite Technologies fell 14.7%, followed by Yes Bank (-14.6%) and HDB Financial Services (-12.9%), making them the biggest losers in the list.
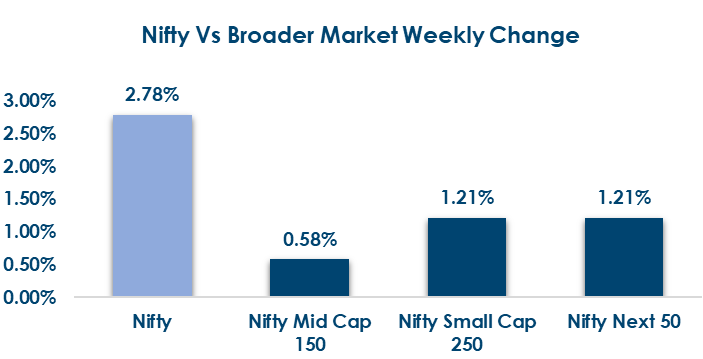
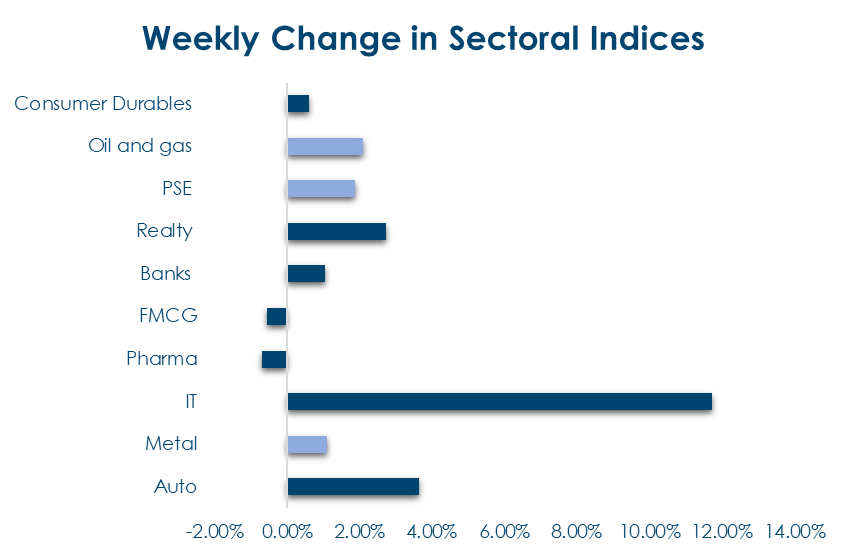
Below are the graphical representations for how key benchmark indices performed this week & how sectoral indices performed this week:
Fixed Income
Global Rates:
- Global 10-year bond yields declined across major economies, led by South Korea (-13.7 bps), the US (-16.5 bps) and France (-9.7 bps), reflecting increased demand for safe-haven assets.
India Rates & Flows:
The 10-year Indian benchmark yield rose to 7.38% from 7.30% last week, while the 1-year OIS climbed to 6.55% amid moderating banking liquidity surplus of ₹2.3 lakh crore.
Real Estate:
Kotak Alternate Asset Managers has begun fundraising for its 15th real estate fund, following the recent close of its predecessor at around $1 billion.
Separately, HDFC Capital and Godwitt Group announced a workforce-housing platform targeting more than 100,000 beds across India’s manufacturing hubs and industrial corridors, highlighting growing institutional interest in rental and workforce housing infrastructure.
IPOs:
- India’s largest-ever IPO opens October 21–23, targeting ₹30,213 crore through a fresh issue, primarily to repay ₹27,500 crore of Reliance Jio Infocomm borrowings. The ₹1,065–₹1,119 price band implies a post-issue market capitalisation of approximately ₹3.38 lakh crore.
- HD Fire Protect (₹712.31 crore) and Fusion CX (₹702 crore) are scheduled to list on October 21, adding over ₹1,414 crore in listing activity alongside the Jio Platforms mega-IPO. Anchor investor participation on October 19 will offer an early indication of institutional demand.
Private Equity & Venture Capital
- Deal value surged to $5.93 billion, driven by Fairfax’s $5.56 billion IDBI Bank acquisition. Excluding this, funding stood at $366.6 million.
- Disclosed-value deals fell to four. Key transactions included Mankind Pharma’s $54 million acquisition of Armed Cell Therapeutics.
Commodities
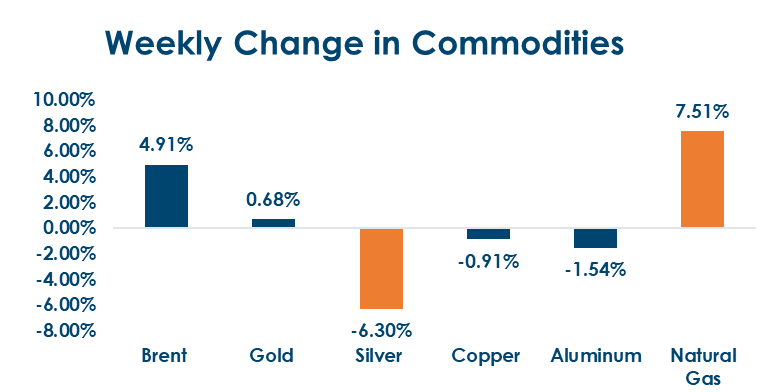
WTI crude surged 10.41% to $101.41, while Brent rose 4.91% to $109.86 and European natural gas gained 7.51%. In contrast, US natural gas fell 3.23%, aluminium and copper declined, while gold slipped 0.68% and silver dropped sharply by 6.30%.
What’s New in the World of Wealth Management
SEBI officially notified the Portfolio Managers Regulations, 2026 via gazette on October 12, effective April 1, 2027. Three changes matter most for HNI and family office clients. PMS portfolios can now include foreign securities including listed overseas equities, foreign government debt, and overseas ETFs, opening global diversification within a domestically managed structure for the first time. PMS managers can now participate in IPOs and primary debt issuances on behalf of clients. And the new PRIM route allows PMS managers to build portfolios using direct plans of mutual funds, ETFs, and SIFs at a Rs 25 lakh ticket size. A common advertising code accompanying the regulations restricts deceptive promises in PMS marketing and mandates investor grievances to be resolved within 21 calendar days.SEBI also tightened governance for India’s Rs 17.53 lakh crore AIF industry this week, introducing a 75% investor consent threshold for key fund decisions and pushing for cleaner separation between fund managers and their distribution arms, directly addressing the conflict that arises when wealth firms act as both product manufacturer and distributor.
Our Views: What we Like?
Equities: We saw short covering this week and domestic equities outperformed global peers on possibility of STT being reconsidered and anti AI sentiment globally. We saw large caps outperform and IT index rebound on anti AI trade and defensives underperformed as risk sentiment improved.Technically 23200 is a very crucial level for Nifty50 on weekly closing basis. We believe the downtrend may still be intact with another test of 22200 likely.
Fixed Income: 1y OIS sold off resulting in OIS curve bear flattening this week. 5y OIS around 6.80% seems attractive to receive. We expect the 10y to trade a 7.15-7.50% range over the next few weeks.
Commodities: Brent prices steadying above USD 100 per barrel is not a good sign and cause of concern for other asset classes as well. Brent prices steadying above USD 100 per barrel is not a good sign and cause of concern for other asset classes as well. We remain neutral to mildly positive on base metals and bullish on precious metals. Current dip in silver is a good buying opportunity in our view.
FX: There are dislocations in forward market as a result of RBI measures, which present arbitrage opportunities.RBI has clearly drawn a line at 97 and we expect the Rupee to trade a 94-97 range over the next few weeks.