Billionz Multi-Asset Weekly Newsletter

Nifty Surges 8.6% as FPIs Return and Money Rotates Out of AI into Indian Large Caps
Global Developments: Democrats captured both chambers in the US midterms, flipping the House and taking the Senate. AI infrastructure names sold off on data center and regulation fears; Kospi, Taiwan and Nikkei ended the week down 11-12%. Trump said he wants to give Iran diplomacy more time before further strikes; Brent fell 16.4% on the week to $98.32, its biggest drop since July. December Fed hike odds jumped to ~75% after strong October payrolls (+165k vs +65k expected). INR assets outperformed on lower crude and rotation out of crowded AI trades.
Domestic Equities
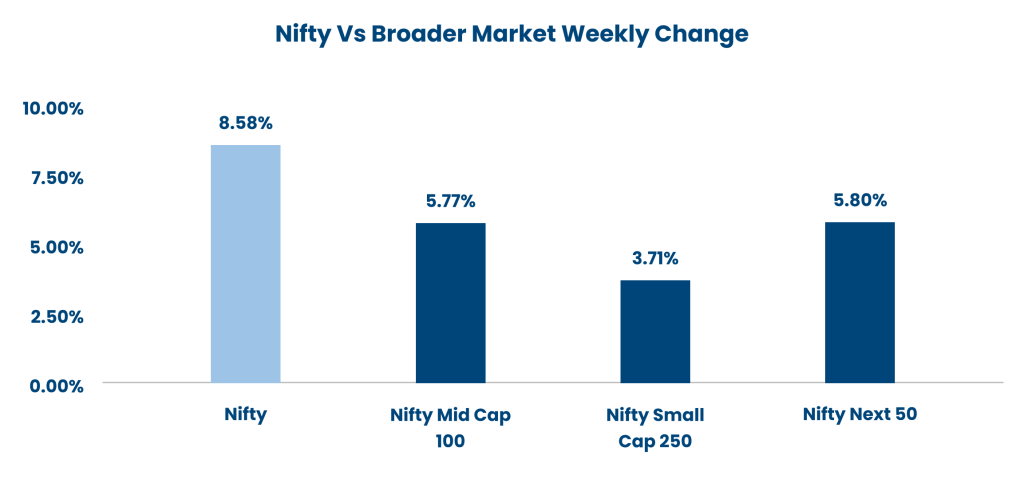
- Nifty 50 trades at 21.9x trailing and 18.6x forward earnings, while Midcap 100 valuations stand at 27.3x and 23.3x, respectively.
- Smallcap 250 trades at 30.1x trailing and 25.5x forward earnings.
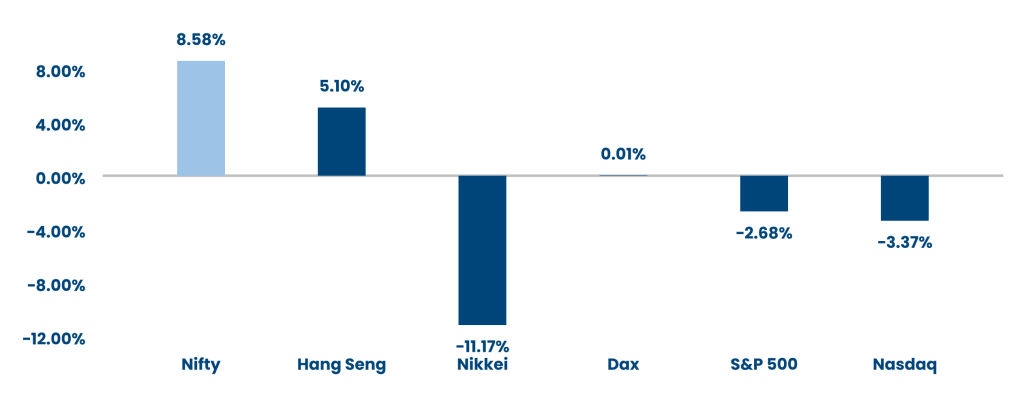
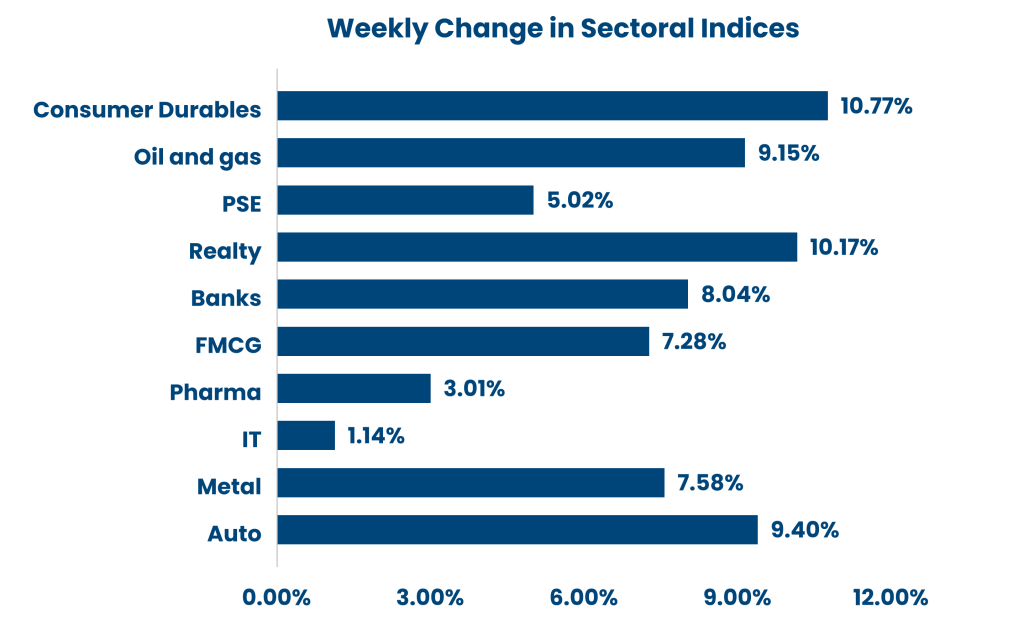
- Nifty 50 gained 8.58% to 25,030, with Consumer Durables (+10.77%) and Fin Nifty (+10.41%) leading a sharp, broad-based rally.
- India VIX jumped to 17.47 compared to last week close of 15.3, even as the market rallied sharply.
- FPIs have bought net USD 4.1bn of domestic equities in November so far.
- HEG Advanced Materials led the gainers with a 23.70% rise, followed by CarTrade Tech at 23.30% and Uma Minda at 22.50%.
- MTAR Technologies fell 20.30%, followed by TD Power Systems at 19.30% and PI Industries at 17.40%.
Below are the graphical representations for how key benchmark indices performed this week & how sectoral
indices performed this week:
Fixed Income
Global Rates: 10-year yields fell across most major economies, led by Japan (-13.9 bps), Australia (-9.9 bps) and France (-2.4 bps), while the US and UK rose 2.3 bps.
India Rates & Flows: The domestic 10-year yield eased to 7.19% from 7.41% as the liquidity surplus widened to ₹1.6-2.3 lakh crore. 1-year and 5-year OIS fell to 6.33% and 6.48%; FPIs bought net USD 400mn of bonds in November.
Alternatives & Real Estate
- Sumitomo Mitsui Trust Bank (SuMiTB) invested in HDFC Capital’s H-DREAM Fund, which targets a corpus of ₹4,250-8,500 crore (~$450-900 million) for affordable and mid-income housing.
- This is SuMiTB’s second commitment to an Indian AIF within a week, after One Planet Partners, showing rising global institutional interest in India’s private markets.
IPOs :
- A record ₹2.23 lakh crore was raised through 375 IPOs in Samvat 2082; Vedant Poly Fabs was the key IPO of 2-6 November.
- Debuts: Bombay Coated and Special Steels, Johnsoncab Electricals, HGS India, Maxwell Engineering Solutions and Vectras Enprocon.
Private Equity & Venture Capital
- Deal value rebounded to $413.3 million across 23 disclosed deals from $120.4 million, led by GIVA (~$100 million) and EloElo ($80 million Series C).
- M&A rose to seven deals from four, led by Adani Ports’ ~$2.88bn acquisition of Evos B.V. and Affle’s ~$420 million bid for Perion.
Commodities
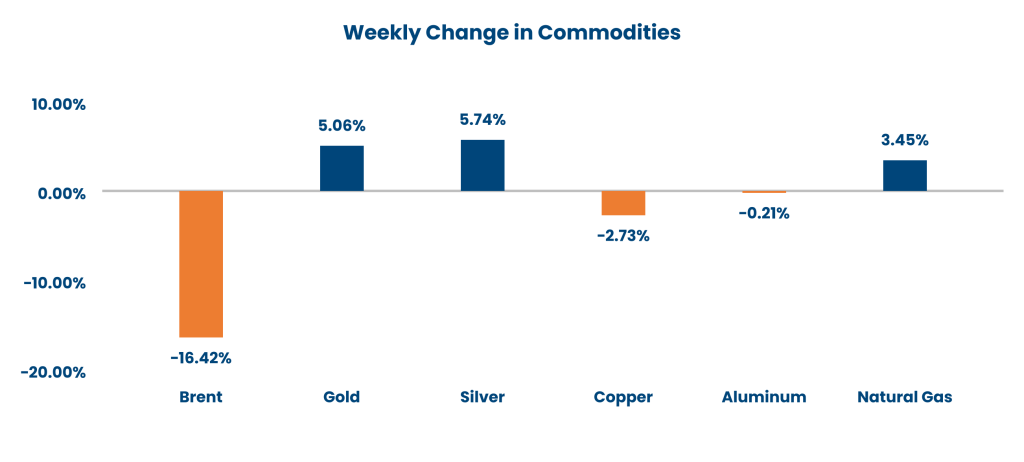
Brent crude fell 16.42% to $98.32/bbl and WTI dropped
12.76%, while European natural gas declined 17.66%
and US natural gas gained 3.45%. Gold rose 5.06% and
silver 5.74%, while copper slipped 2.73% and
aluminium 0.21%.
What’s New in the World of Wealth Management :The IPO market remained strong, with a record ₹2.23 lakh crore raised through 375 IPOs in Samvat 2082, although fresh issuance moderated after the Jio Platforms listing. SEBI is also reviewing the Issue of Capital and Disclosure Requirements (ICDR) framework governing mainboard IPOs. Vedant Poly Fabs was the key IPO of 2-6 November, while Bombay Coated and Special Steels, Johnsoncab Electricals, HGS India, Maxwell Engineering
Solutions and Vectras Enprocon made their market debuts.
Our Views: What we Like?
Equities : Nifty50 ended 2.0% higher at 25030 on Friday, taking its gain for the week to 8.6%. In Sunday’s Muhurat trading session, Nifty50 ended 0.2% lower at 24986 relative to Friday’s close. Broader NSE500 ended 0.1% higher with a breadth of 154-341-5 in favor of advances. Midcap100 index ended 0.1% higher while Smallcap250 index ended 1.2% higher. India VIX ended at 18.43 relative to previous close of 17.47. Among sectoral indices, pharma outperformed while banks and IT underperformed. GIFT is indicating a flat open for Nifty50.
Bonds and Rates : Yield on the benchmark 10y ended 2bps higher at 7.19% on Friday, while 1y and 5y OIS ended 7bps and 5bps lower at 6.33% and 6.48%, respectively.
Commodities: We have been advising long precious metals, a call which has faced headwinds. However, we stick to that view
and strongly believe it should be a part of portfolio allocation. Crude has again fizzled out around USD 120 and
that remains a major hurdle. We are bullish on base metals as well.
FX : We expect Dollar strength against majors. Though Democrat victory is widely seen as Dollar negative, we believe it instils confidence in Dollar and is negative for De-Dollarization bets.